Four Strategies Worth a Second Look: Takeaways from the UFAN Gator Gathering Advisor Panel
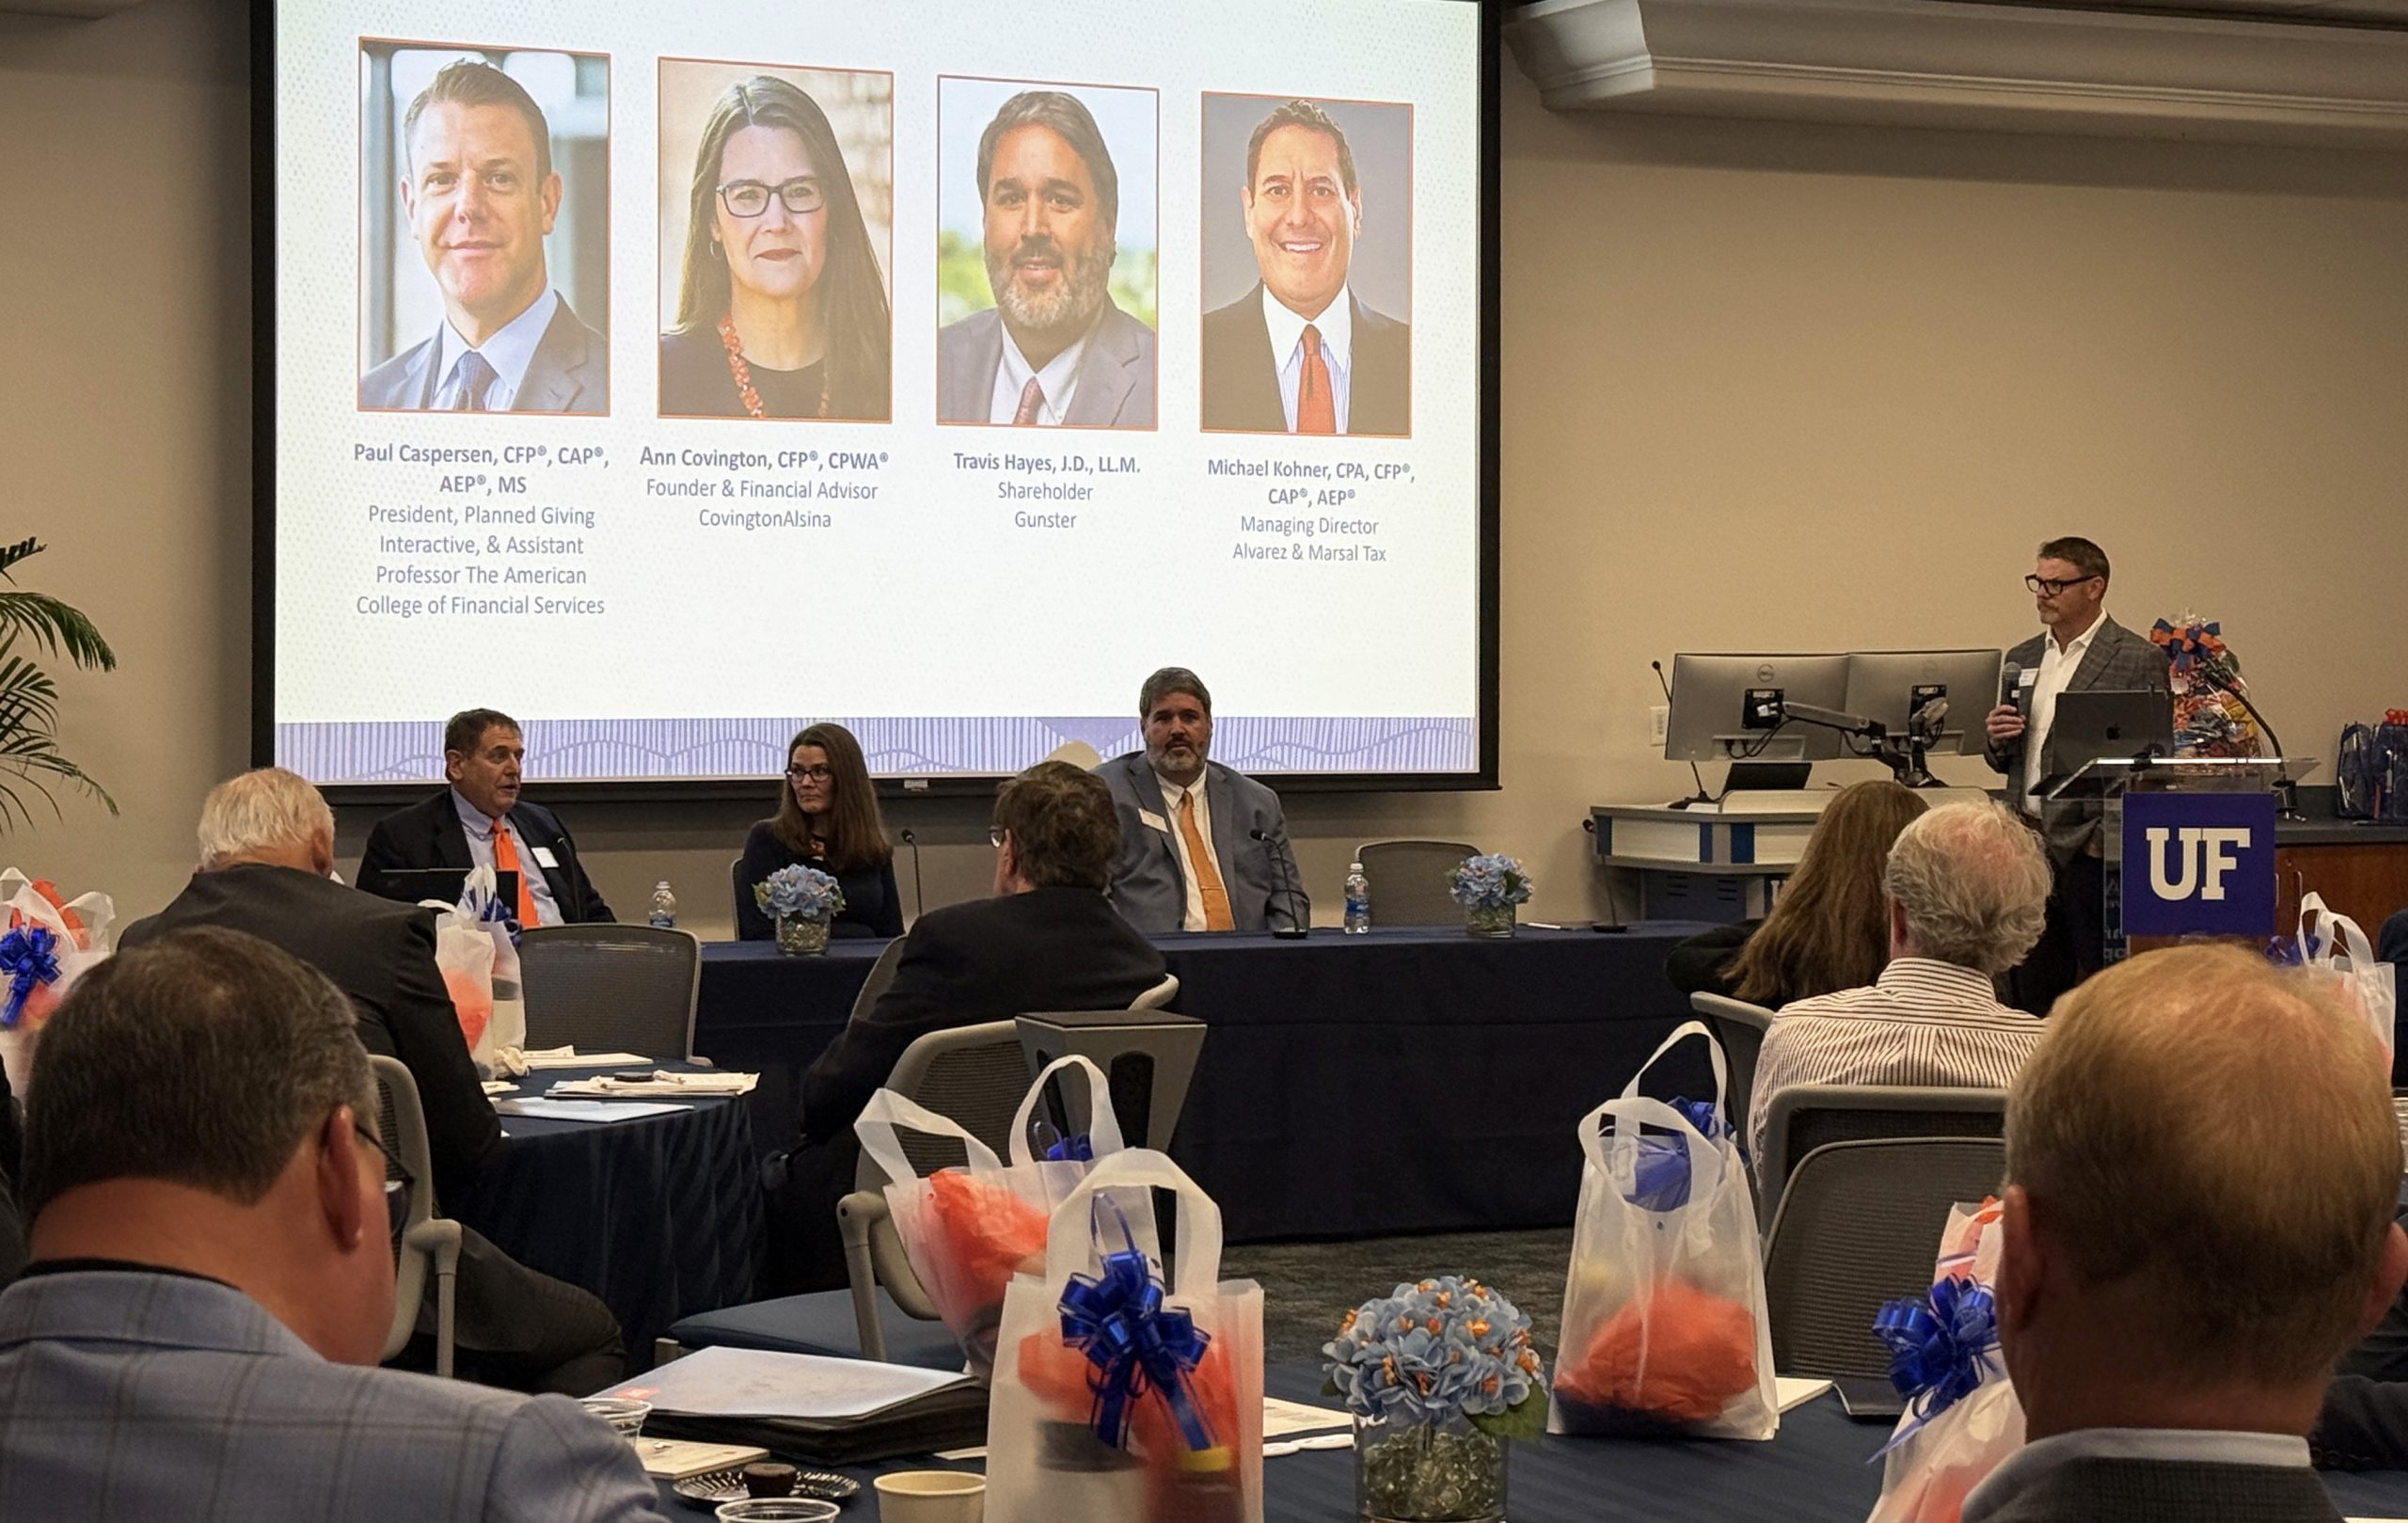
At this year’s UF Advisor Network (UFAN) Gator Gathering Annual Conference on Friday, May 29, I had the pleasure of moderating a panel of three accomplished advisors who shared candid ideas and best practices with an engaged audience. The room clearly respected the depth of experience on stage, and the conversation ranged widely. Four strategies in particular stood out as worth a closer look, and each deserves a fuller explanation for advisors who want to put these ideas to work.
Our panelists were Travis Hayes, a Shareholder at Gunster in Naples whose trusts and estates practice includes service as an ACTEC Fellow and as primary drafter of the Florida Community Property Trust Act; Michael Kohner, a Managing Director with Alvarez and Marsal Tax in West Palm Beach with more than 38 years advising family offices, venture capital firms, and high net wealth families; and Ann Covington, CFP, CPWA, of CovingtonAlsina, a Fisher School of Accounting graduate who divides her practice between Maryland and Jacksonville and serves on the UF Alumni Association Board of Directors. Fittingly for a UFAN gathering, all three panelists hold at least one University of Florida degree, and a few are double Gators.
Bunching charitable gifts through a donor-advised fund
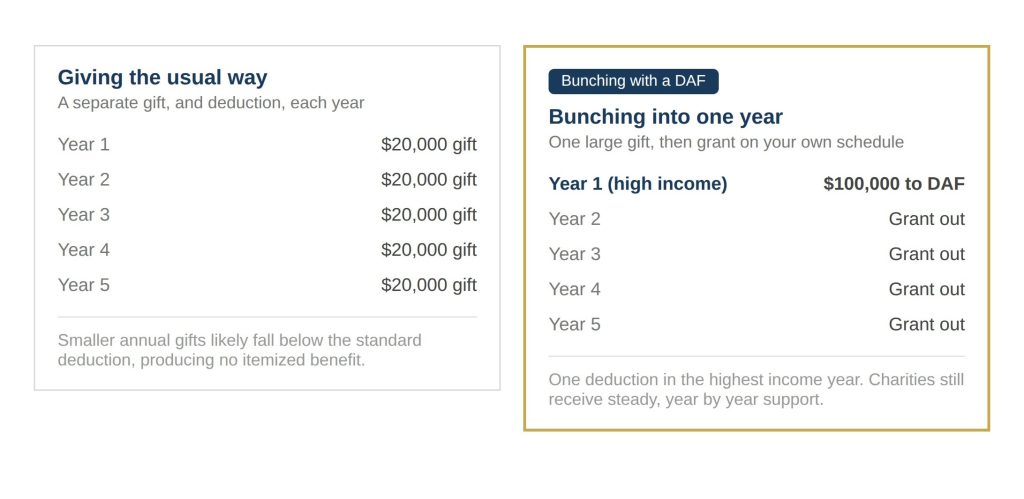
Ann opened with a strategy she uses with many of her clients: being deliberate about the timing of charitable gifts. Rather than giving the same amount every year, she encourages clients to concentrate, or “bunch,” several years of intended giving into a single high-income year. The technique pairs naturally with a donor-advised fund (DAF). The client makes one large, front-loaded contribution to the DAF in the year the deduction is most valuable, then recommends grants to the charities they care about over time, on their own schedule. The tax benefit is captured up front when income (and the marginal rate) is highest, while the actual support of charities continues at a comfortable pace.
The case for bunching is strongest precisely because of how the standard deduction works. A donor giving $20,000 a year is unlikely to clear the standard deduction threshold, which means those annual gifts produce no itemized tax benefit at all. Concentrate five years of giving into one, and the donor itemizes in that single year and captures the deduction that the smaller annual gifts would have wasted. The timing can be sharpened further by pairing the contribution with a year of unusually high income, the sale of a business, a large bonus, a Roth conversion, or the exercise of stock options, so the deduction offsets income taxed at the top rate. Funding the DAF with appreciated securities rather than cash adds a second layer of benefit, since the donor avoids the capital gains tax on the appreciation while still deducting the full fair market value. Ann noted that clients are simply happier when they approach philanthropy this way, because the giving feels intentional rather than rushed, and the DAF gives them time to think carefully about where their grants will do the most good.
Community property trusts in Florida
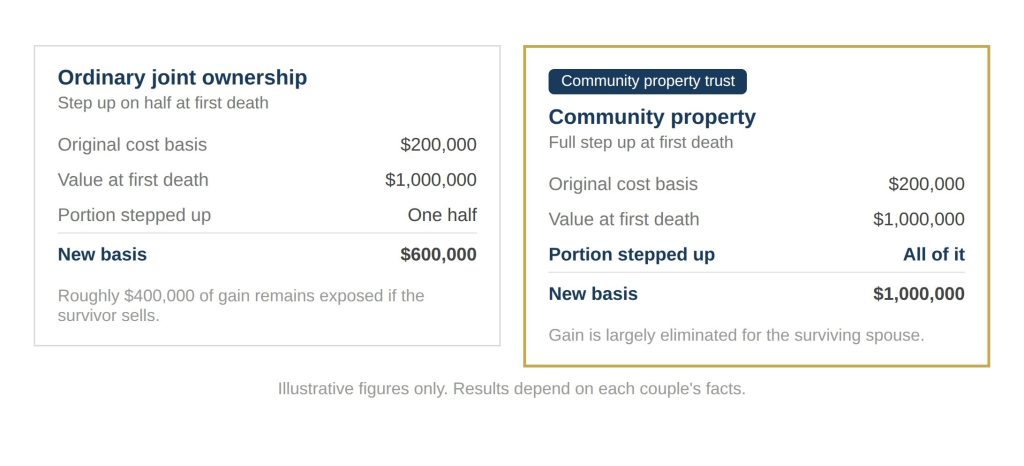
Travis Hayes turned to a development many Florida advisors have not yet fully absorbed. Florida now has a community property statute[1], and where it fits, Travis is incorporating community property trusts into his clients’ planning. The central appeal is income tax basis. Assets held as community property can receive a full step up in basis on the death of the first spouse, not just a step up on the deceased spouse’s half. For couples holding highly appreciated assets, a long-held brokerage account, a closely held business interest, or real estate that has grown substantially in value, that difference can deliver a meaningful reduction in capital gains exposure for the surviving spouse who later decides to sell.
Travis was careful to frame this as a tool for the right situations rather than a universal solution. It tends to make the most sense for married couples with strong, stable marriages, highly appreciated assets they may want to sell after the first death, and a level of comfort with the idea of converting separate property into community property, which carries its own legal consequences. I asked how a community property trust can coexist within a common law state like Florida, and his answer was a matter of discipline: you keep the community property trust and its assets clearly separate from the couple’s other assets, so the character of each is never in doubt. Clean records, separate titling, and careful funding are what preserve the favorable treatment if the IRS ever looks closely. Where it applies, the benefit can be substantial.
Establishing Florida residency the right way
Michael Kohner addressed a challenge that arises constantly in a state like Florida: clients moving from high tax states such as California or New York who want to claim Florida residency. The difficulty is that the departed state often does not let go easily. With no state income tax of its own, Florida is an attractive destination, but the former home state has every incentive to argue that the client never truly left, and an aggressive residency audit can reach back years. Michael walked through the detailed checklist that separates a genuine change of domicile from one that invites an audit, covering the many intimate details that establish where a person truly lives: where you spend your nights, where your physician and dentist are, where your cars are registered, where you vote, where your family gathers for the holidays, and where the possessions you treasure most are kept. No single item is decisive. The picture is built from the whole pattern of a person’s life.
Ann added a memorable personal example. After years of practicing primarily in Maryland while keeping an office in Jacksonville, she recently made the decision to become a Floridian again, and she now keeps an app on her phone that tracks exactly how much time she spends in each location. That kind of contemporaneous record is precisely the evidence that holds up when residency is questioned, because it is far more persuasive to a skeptical auditor than a recollection assembled after the fact.
Leaving a retirement plan to a testamentary charitable remainder trust
Travis closed with one of the most strategic ideas of the day. For clients with charitable intent whose retirement plans represent a large share of their estate, he discussed naming a testamentary charitable remainder trust (CRT) as the beneficiary of some or all of an IRA. The trust pays income to the client’s loved ones, usually adult children, for life, with the remainder passing to the charities the client cares about. In effect, this reengineers the stretch that is no longer available to most non-spouse beneficiaries under current rules, restoring a lifetime income stream while fulfilling a charitable goal.
The appeal becomes clearer when you consider the alternative. Under current law, most adult children who inherit an IRA must empty the account within ten years, often during their own peak earning years, which can push the distributions into high tax brackets and compress a lifetime of tax deferred growth into a single decade. By routing the IRA to a testamentary CRT instead, the client can spread payments to those same children across their lifetimes, smoothing the income and the tax, while the assets continue to grow inside a tax-exempt trust. The charity receives whatever remains at the end of the income term. For the right client, one who genuinely wants to provide for children and also has charitable intent, is a way to do both with assets that would otherwise be among the most heavily taxed in the estate.

On this last point, I will add a personal note. Having led and built the gift planning team at the University of Florida between 2012 and 2022, I am exceptionally proud of this group. They have continued to exceed expectations, improving year after year in both experience and in their productivity serving the university. The UF Office of Estate & Gift Planning has deep, hands-on experience with testamentary charitable remainder trusts, and with the full range of strategies discussed here.
So, my encouragement goes beyond the CRT. If you have a client with a connection to the University of Florida, and you see an opportunity where the right charitable strategy could do well by your client and create a meaningful impact, reach out to the gift planning team. Whether it is a bunching plan through a donor-advised fund, a gift of appreciated or complex assets, a charitable remainder trust, or simply a conversation about what is possible, that team is a genuine resource and a strong collaborator. Some of the best outcomes I have seen came from an advisor and a gift planning professional working a situation together, each bringing what they know best to the table. The conversation is worth your time, and your clients will be the better for it.
Paul Caspersen is an Assistant Professor at The American College of Financial Services. He is also Vice President and advisor at Charitable Solutions, LLC, a national consulting firm that supports charities in accepting complex charitable gifts and developing charitable trusts. Paul is the Founder of Planned Giving Interactive, an AI software and advisory firm that is an affiliate company of Charitable Solutions, LLC.
[1] Fla. Stat. §§736.1501-736.1512 (2025)
The UF Foundation (federal tax ID number 59-0974739) is a Florida nonprofit organization exempted from federal income tax as a 50l(c)(3) publicly supported charity. The UF Foundation does not provide legal, tax or financial advice. When considering planning matters, seek the advice of your own legal, tax or financial professionals.
Information contained herein was accurate at the time of publishing. The information in this publication is not intended as legal or tax advice. For such advice, please consult an attorney or tax advisor. Figures cited in any examples are for illustrative purposes only. References to tax rates include federal taxes only and are subject to change. State law may further impact your individual results.